Only 20% of GE Vernova's Order Book Is Data Centers. Here's Why That's the Bull Case, Not the Risk.
 2026-10-07 15:34
•James Brumley •The Motley Fool
•••••• •
Axe Cap view
GE Vernova’s Balanced Backlog: A Strength, Not a Risk
GE Vernova’s limited exposure to AI data centers amid robust traditional power demand underpins sustainable growth.
GE Vernova’s order book is often viewed through the AI lens, but only 20% relates to data centers. The rest comes from steady sectors like utilities and refineries, sectors that grow with electricity demand, not just hype. South Africa’s power sector challenges remind us that reliable generation capacity has real, lasting value. With global electricity needs growing around 3.7% annually through 2027, thanks to electric vehicles and cooling systems, GE Vernova’s diversified customers mean its growth isn’t tied to a single trend. Morningstar’s forecast of revenue doubling by 2030 is ambitious but plausible given these drivers. Currency-wise, a sustained USD/ZAR near current levels supports the affordability of imports including power tech. However, if global energy demand softens or cheaper alternatives gain rapid ground, this view could falter. Still, GE Vernova looks more like a long-term structural play than a bubble-risk bet. this is just our opinion and not financial advice
Consider watching GE Vernova for a buy on any meaningful pullback, balanced by how USD/ZAR trends impact cost inflation. For South African investors, focus remains on more direct domestic generators but keep an eye on global power tech for diversification.
- GEV
- USD/ZAR
- slowing global electricity demand growth
- emergence of disruptive cheaper energy technology
6/10
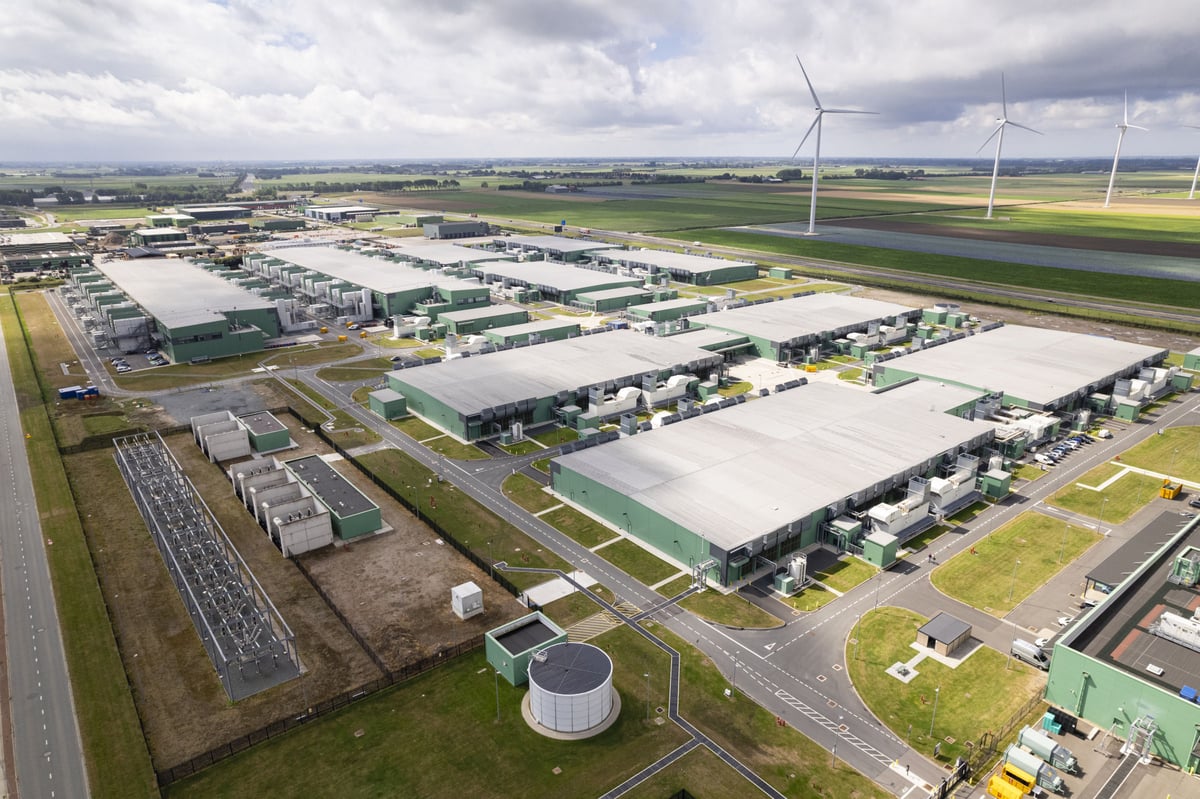
GE Vernova derives only 20% of its power-generation backlog from AI data centers, with the remaining 80% coming from traditional customers like utilities and refineries. While AI demand provides pricing power, the company's diversified customer base insulates it from AI market volatility. With global electricity demand expected to grow 3.6-3.8% annually through 2027, driven by EVs and other factors beyond AI, GE Vernova is positioned for sustainable long-term growth, with Morningstar projecting 2030 revenue of $78.6 billion versus $38.1 billion in 2025.
Our take is based on reporting first published by The Motley Fool.