ARM vs. Marvell Technology: What Revenue Trends for These Artificial Intelligence Companies Tell Investors
 2026-10-07 17:35
•Robert Izquierdo •The Motley Fool
••••• ••
Axe Cap view
Marvell’s AI Momentum Outpaces ARM’s Pivot
Marvell's steady growth outshines ARM’s uneven AI transition, but both face distinct challenges.
Marvell Technology’s recent revenue growth paints a picture of a company thriving on AI-driven demand. Its focused play in custom chips for cloud giants gives it a solid edge, demonstrated by steady quarterly gains and bullish guidance through FY2031. That scale and predictability should appeal to investors hunting growth on the JSE, especially compared to ARM. ARM’s shift from mobile licensing to data center CPUs is interesting but still a work in progress; the uneven revenue hurts confidence, and it’s unclear if the pivot will fully materialize before competitive pressures mount. Locally, the broader technology exposure from companies like Naspers and Prosus means we're more comfortable linking AI trends to Marvell’s performance rather than ARM’s uncertain path. Of course, if major data center customers delay deployment or chip shortages return, Marvell’s growth could stall. this is just our opinion and not financial advice
We would watch Marvell for potential inclusion as a proxy to ride AI chip demand, while remaining cautious on ARM until its revenue stabilizes. On the JSE, keep an eye on Naspers and Prosus for indirect AI exposure. USD/ZAR movements will also reflect risk appetite tied to global tech cycles.
- MRVL
- Naspers
- Prosus
- USD/ZAR
- Slower adoption of AI data centers
- Renewed global semiconductor supply constraints
6/10
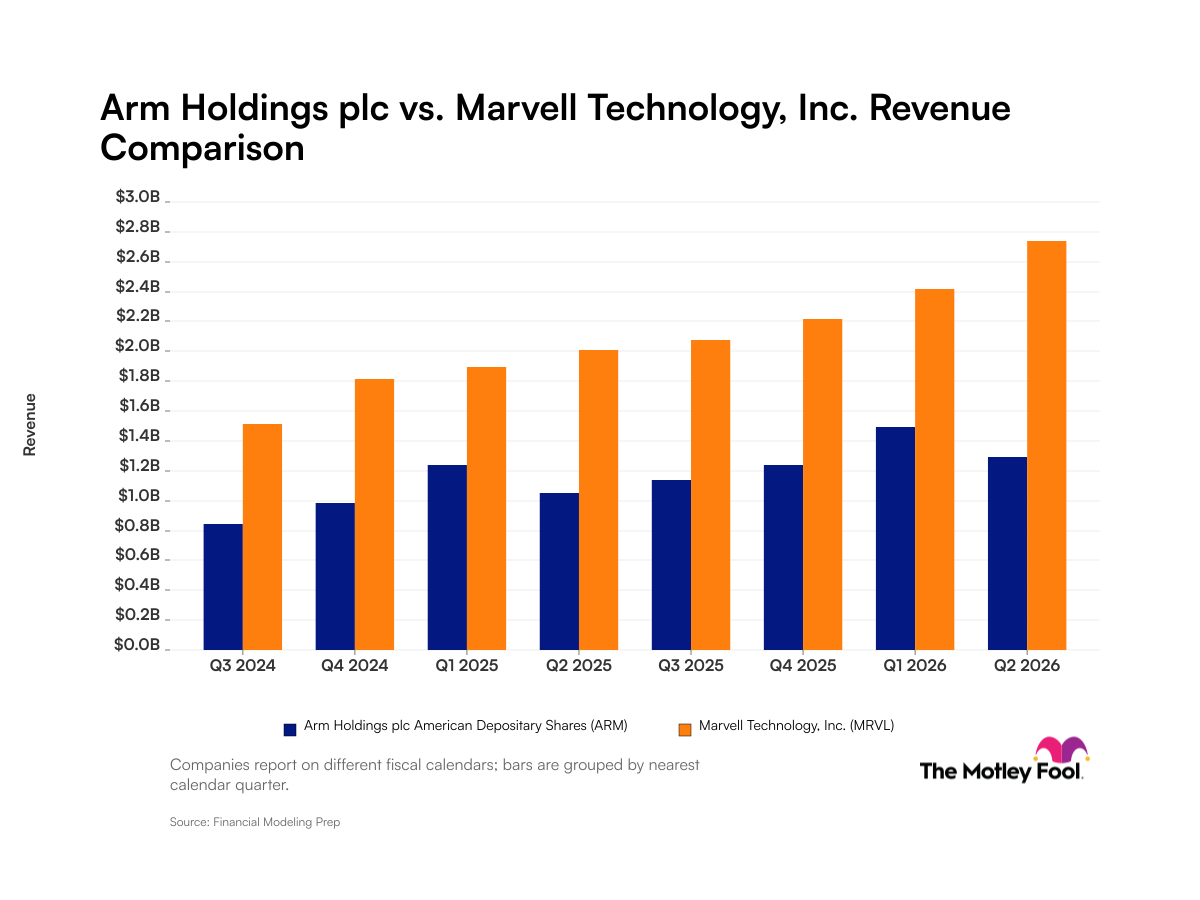
Marvell Technology demonstrates stronger revenue growth than ARM, with consistent quarter-over-quarter increases driven by high demand for its AI-related semiconductor solutions from tech giants. ARM shows more uneven growth patterns but recent quarters suggest acceleration as it pivots toward data center CPU production. Marvell raised its FY2028 revenue outlook to $20 billion and projects $70-90 billion by FY2031, indicating confidence in sustained growth.
Our take is based on reporting first published by The Motley Fool.